Your employer has put two numbers on the table — a monthly pension for life, or one large lump sum — and the honest answer to “which is better?” is: it depends how long you live, and any tool that hides that is selling you something. This calculator hides nothing. It lays both offers side by side, year by year, and prints BOTH endings.
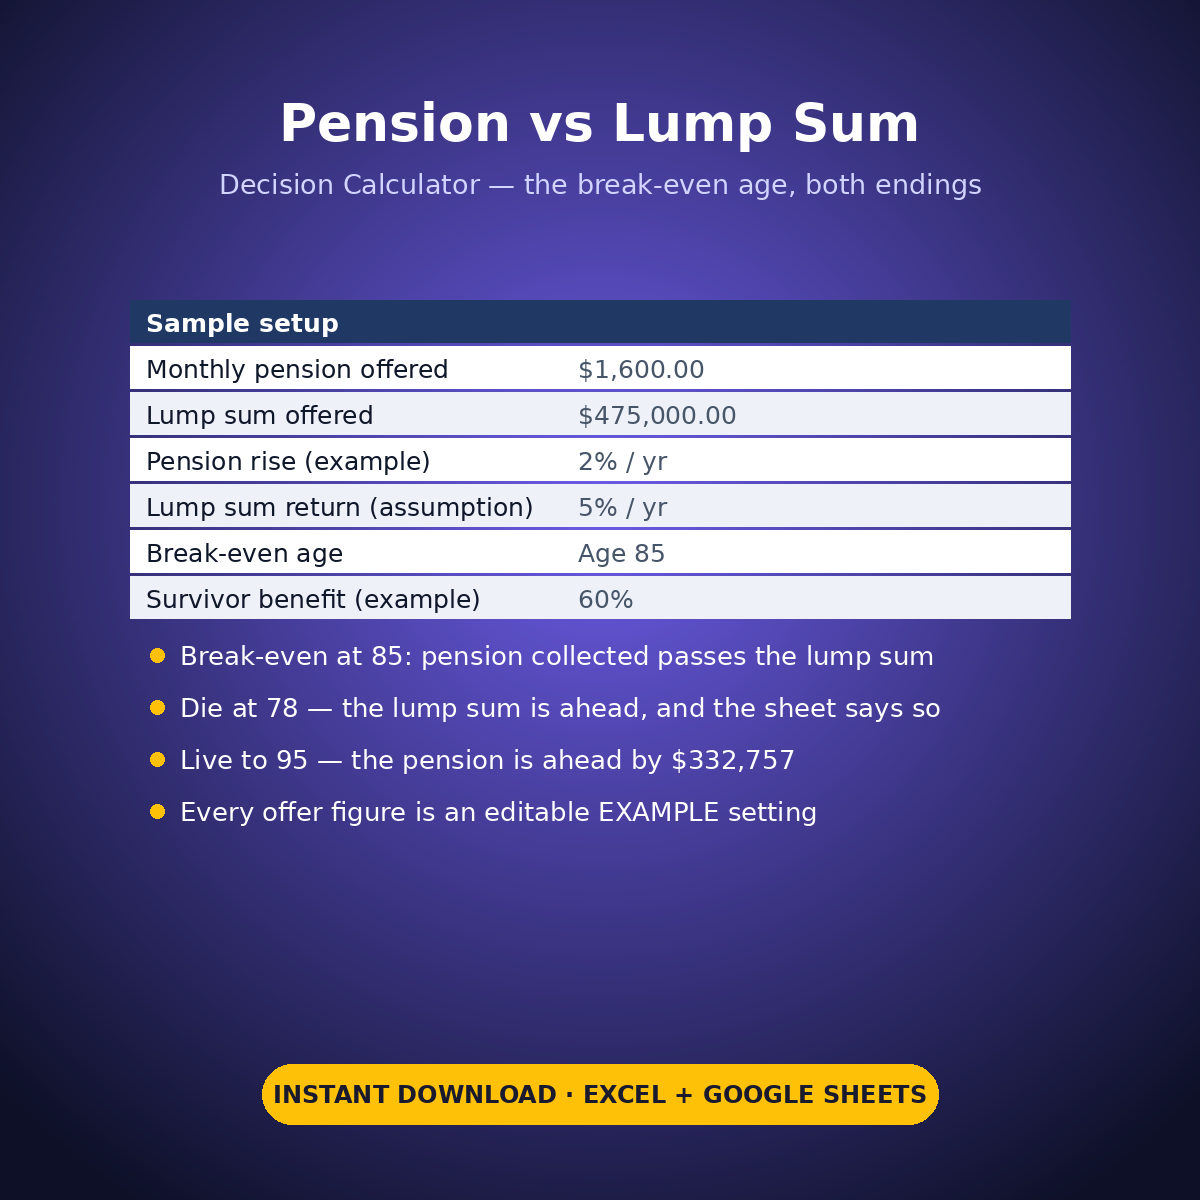
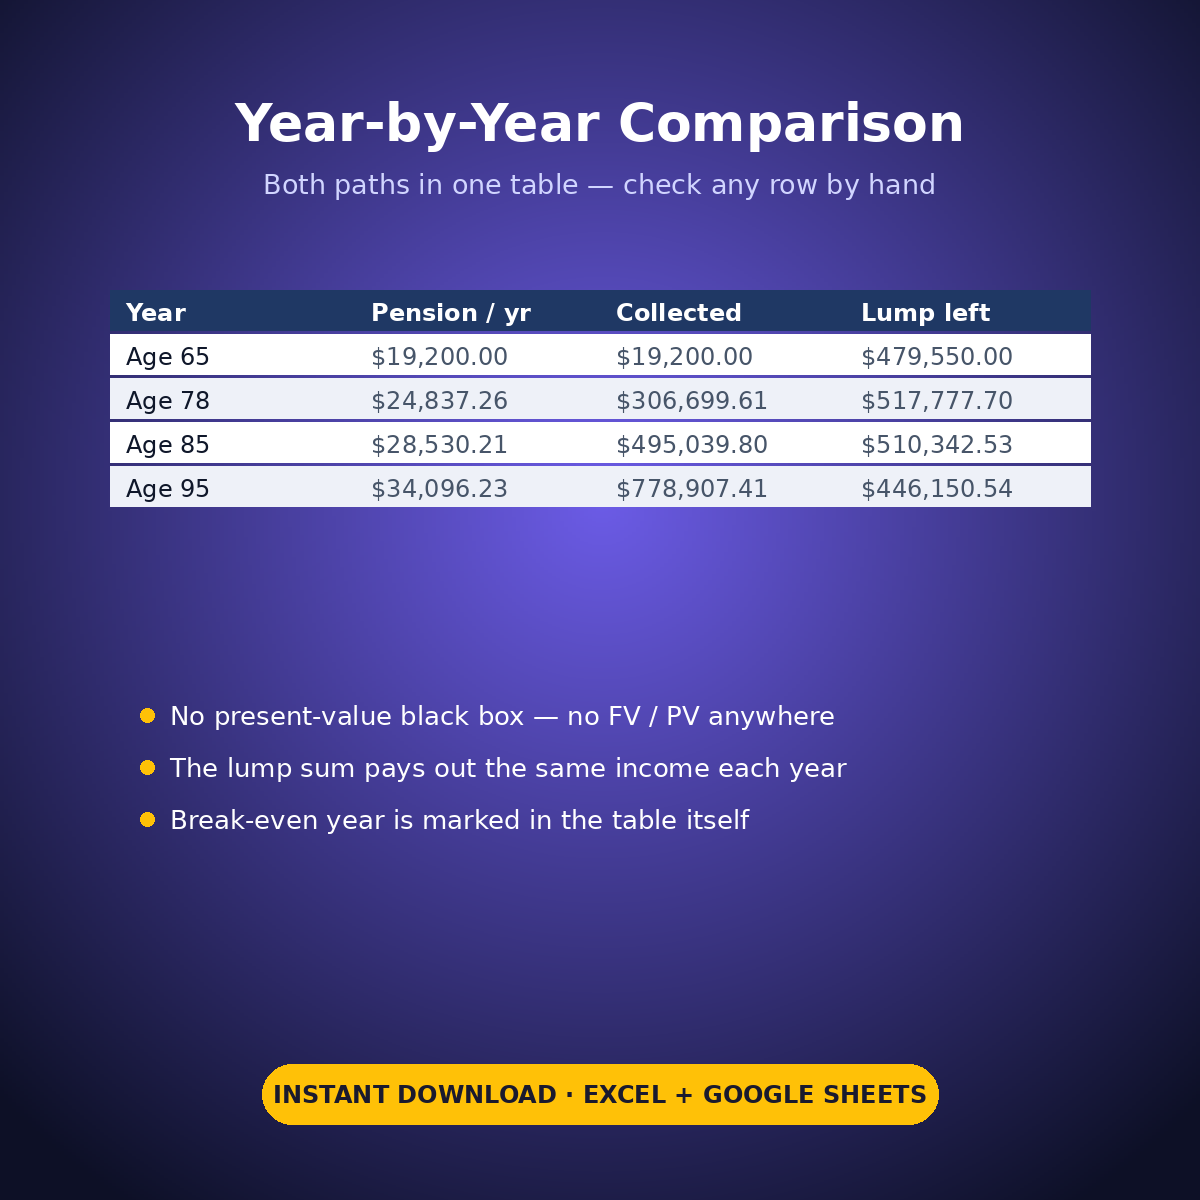
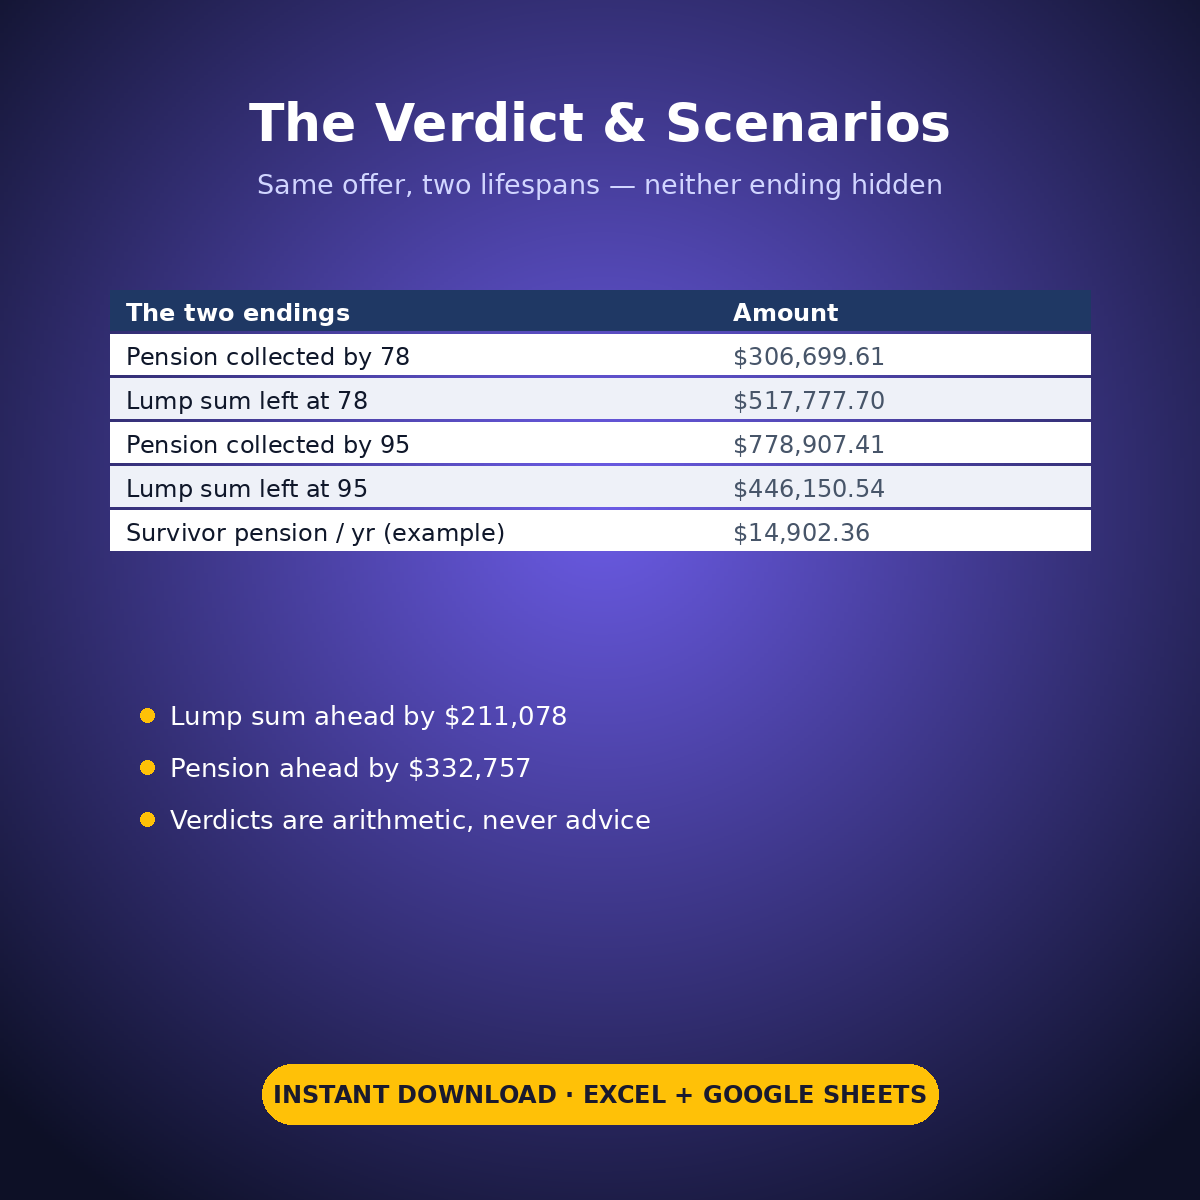
The sample offer: $1,600 a month starting at 65, rising at an EXAMPLE 2% a year, against a $475,000 lump sum invested at YOUR assumed 5% return, paying out the same income each year. The break-even age — where the pension collected so far passes the lump sum offered — is 85. Die at 78 and the lump sum is ahead, and the sheet says so in figures: $306,699.61 of pension collected against $517,777.70 still left in the lump-sum pot. Live to 95 and the pension is ahead by a wide margin: $778,907.41 collected against $446,150.54 left. Same offer, two lifespans, both printed.
A survivor line is included, because the decision is rarely one person’s: at the EXAMPLE 60% survivor setting (typed from the offer letter — yours may differ), a death at 78 leaves a spouse $14,902.36 a year from the pension, while the lump-sum path leaves its $517,777.70 remainder to the estate. The sheet compares the amounts; it never tells you which to choose, and it says so on the page.
Every figure that comes from the offer — the pension amount, its cost-of-living rise, the survivor percentage — is a yellow EXAMPLE setting pre-filled from a sample offer letter, with instructions to verify against your own documents and replace it. The return on the lump sum is labelled what it is: your assumption, not a promise. There is no present-value black box anywhere — no FV or PV functions; the comparison is a visible year-by-year table you can check with a pencil.
What it does for you:
– Compares pension vs lump sum year by year: pension paid and collected, lump sum grown and drawn down in the same table
– Prints the break-even age (85 in the sample) where cumulative pension passes the lump sum
– Shows both endings honestly — ahead-at-78 and ahead-at-95 figures, neither hidden
– Adds the survivor-benefit scenario at your offer’s own percentage
– Every offer figure is an editable EXAMPLE setting — replace them all and every number recomputes
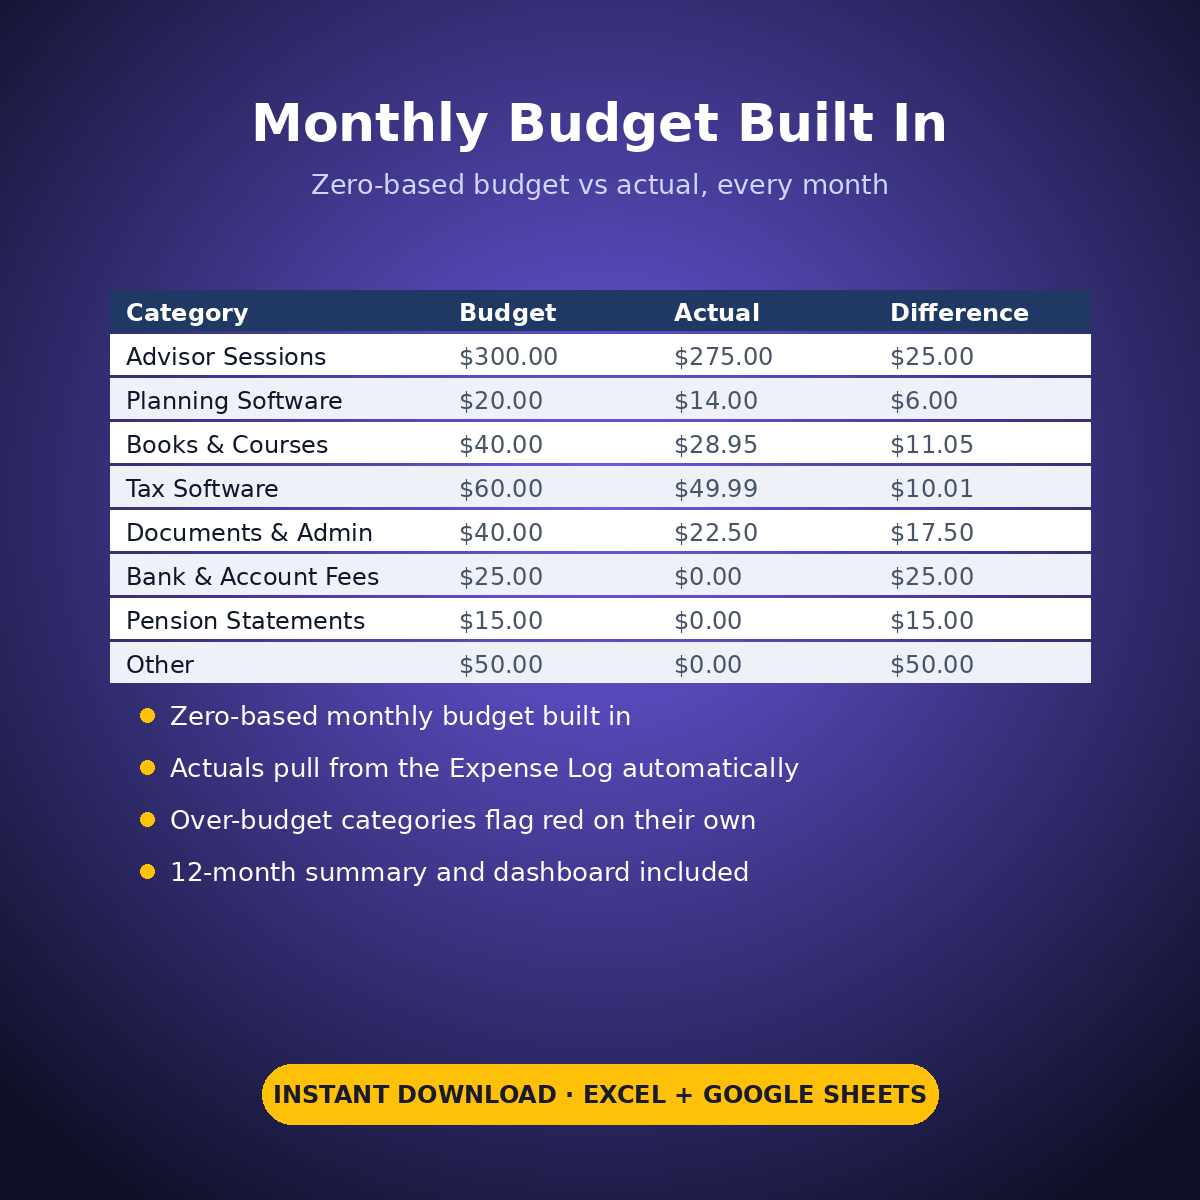
– Plus expense log, zero-based monthly budget, dashboard and monthly summary
What’s inside (.xlsx, works in Excel AND Google Sheets):
– Start Here — setup steps and the offer settings (all EXAMPLES, verified against your own offer letter)
– Year-by-Year Comparison — 40 years of both paths side by side, with the headline block
– Verdict & Scenarios — the two endings and the survivor line, in print
– Expense Log, Monthly Budget, Dashboard, Monthly Summary
Instant download. Type only in the yellow cells — formula cells are locked (password: sheetdaily, disclosed on the Start Here tab so you can unlock if you ever need to). Sample offer is pre-filled so you can see exactly how it works; clear the yellow cells and type your own. Planning tool only — not financial advice; tax, health cover and flexibility are not in this sheet and matter in the real decision.
Reviews
There are no reviews yet.