
Saving the portfolio was only half the problem. The other half is spending it without running out — and the famous 4% rule answers that question for exactly one level of spending. This planner runs the drawdown twice, side by side, so you can see what the rule sustains and what it cannot.
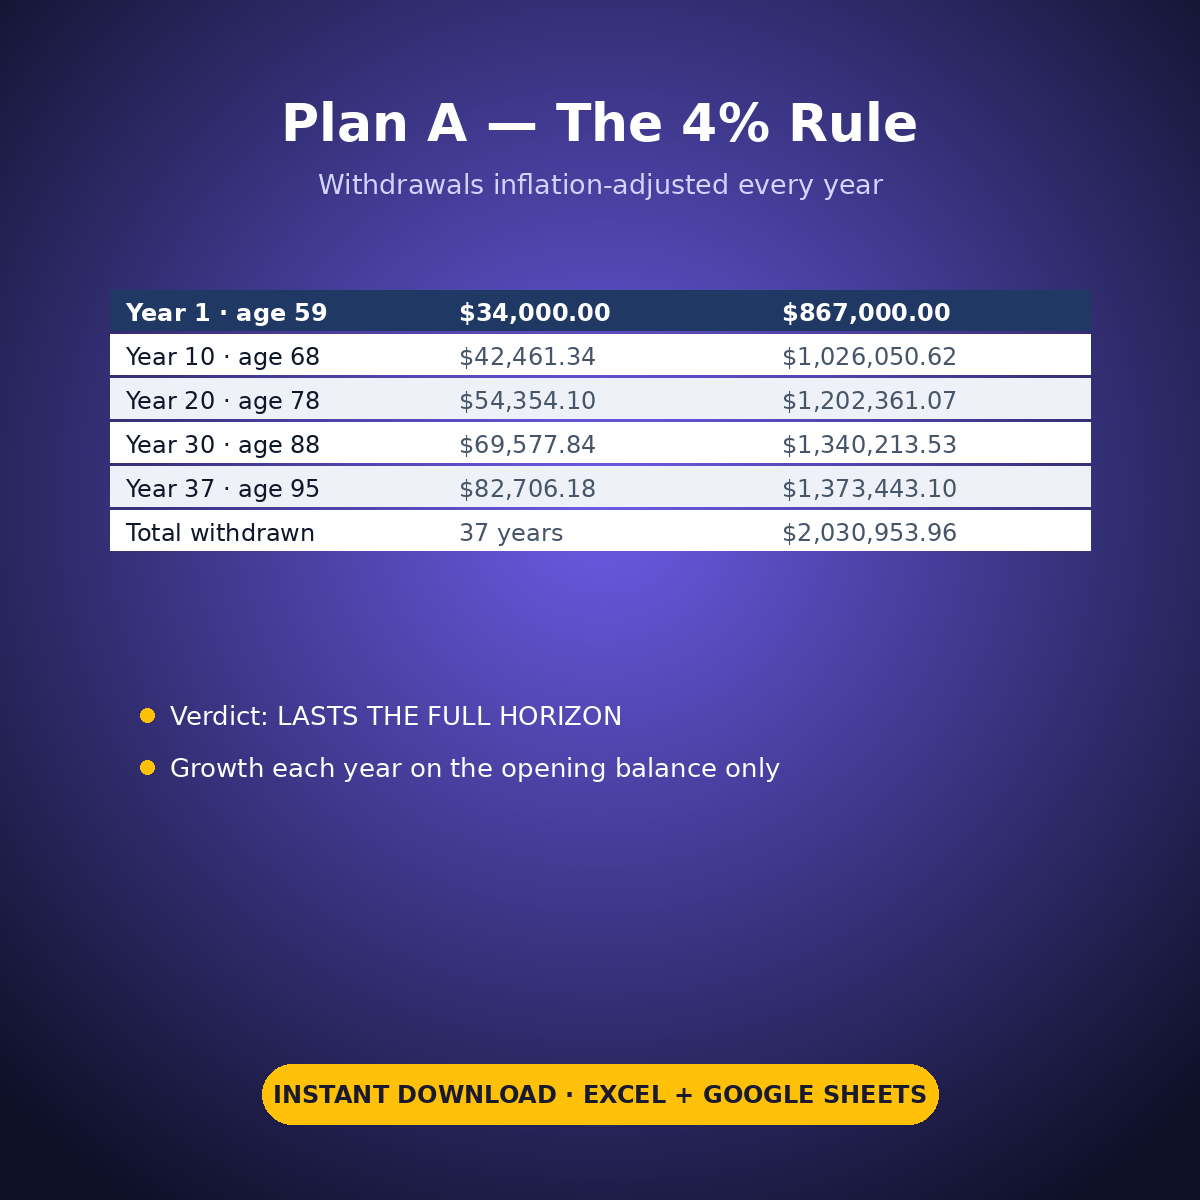
Plan A is the rule itself: withdraw 4% of the starting portfolio in year one — $34,000 on the sample’s $850,000 — then adjust that amount for inflation every year. Thirty-seven visible rows walk from age 58 to the age-95 horizon: balance, that year’s growth, the withdrawal out, what is left. At the sample’s EXAMPLE 6% return the money lasts the full horizon — $1,373,443 still invested at 95, after $2,030,954 of total withdrawals. It lasts because the assumed return outruns a withdrawal that started at 4% of the ORIGINAL portfolio, and the sheet shows you that arithmetic instead of asking you to trust it.
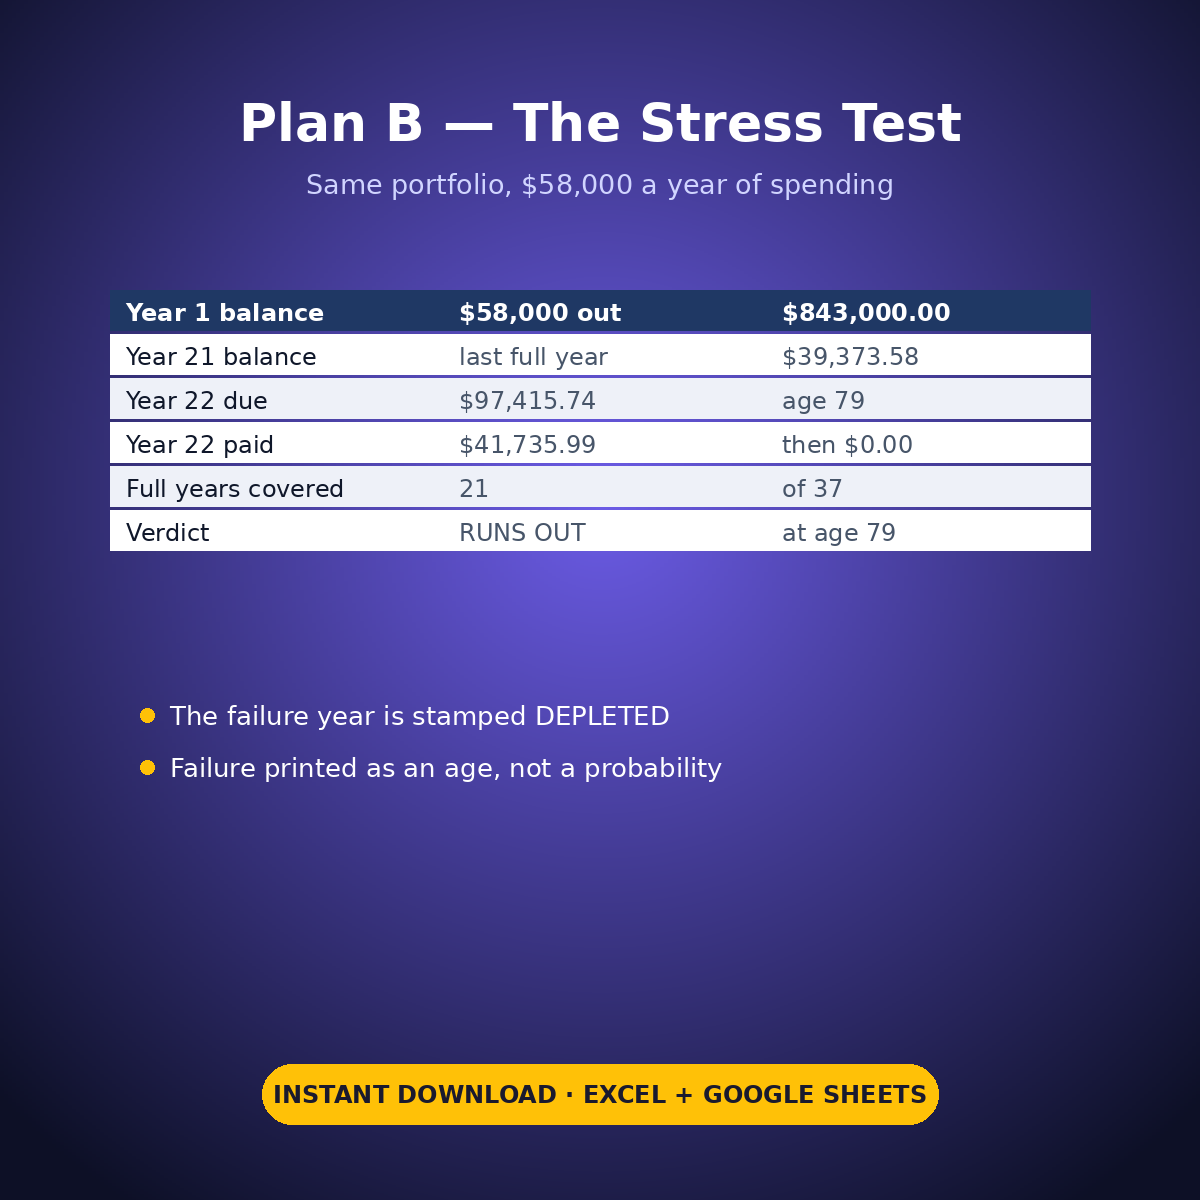
Plan B is the stress test nobody puts on the cover: the same portfolio, the same return, but $58,000 a year of spending. The money covers 21 full years and runs out at age 79. In year 22, only $41,735.99 of the $97,415.74 withdrawal can be paid, and the row is stamped DEPLETED — not averaged away, not softened. The $24,000-a-year difference between the two first-year withdrawals is the difference between a portfolio that outlives you and one that does not, at these assumptions.
Every assumption is yours to change: starting portfolio, start age, horizon, return, inflation, the Plan A withdrawal rate, the Plan B spending, and whether withdrawals inflation-adjust at all. Change one and both plans reprice instantly — the run-out age moves, the verdict rewrites itself.
What it does for you:
– Runs the 4% rule as an explicit year-by-year drawdown — 37 auditable rows, no black box
– Runs a second, higher-spending plan against the same portfolio as a built-in stress test
– Prints the run-out age and stamps the DEPLETED row when a plan fails — failure is a number, not a vibe
– Totals the withdrawals across the whole plan ($2,030,954 in the Plan A sample)
– Inflation-adjustment is a toggle; return and inflation are EXAMPLE assumptions you own
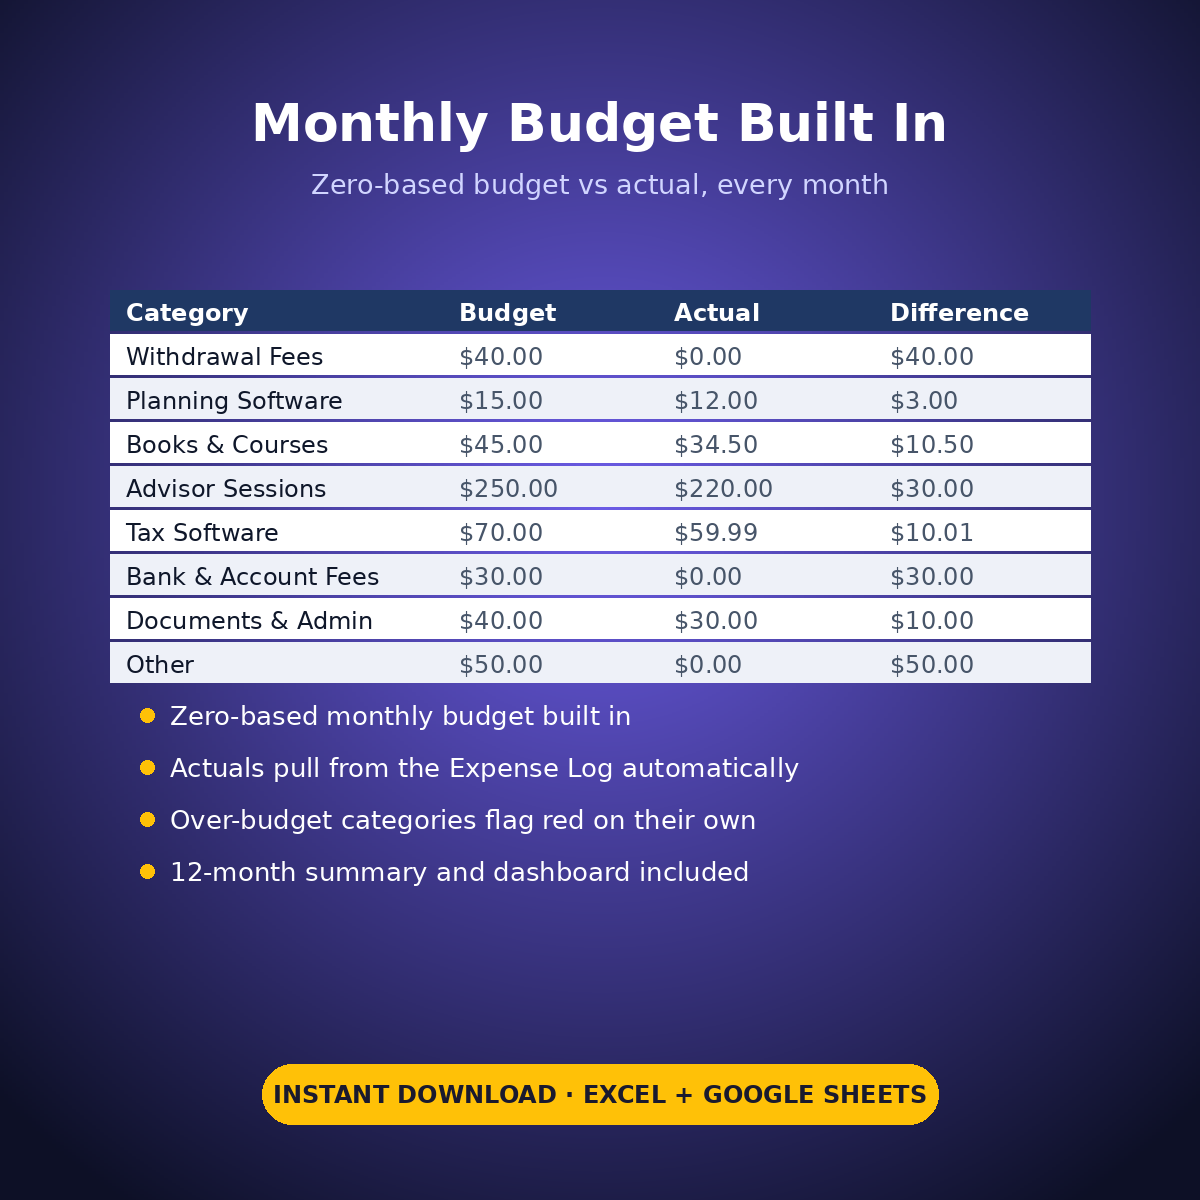
– Adds a planning expense log, zero-based monthly budget, dashboard and 12-month summary
What’s inside (.xlsx, works in Excel AND Google Sheets):
– Start Here — setup steps and every EXAMPLE setting (portfolio, ages, return, inflation, rate, Plan B spending, the toggle)
– Plan A Drawdown — the 4% rule year by year, with the verdict block
– Plan B Drawdown — the higher-spending plan, its run-out age and its verdict
– Expense Log, Monthly Budget, Dashboard, Monthly Summary
Instant download. Type only in the yellow cells — formula cells are locked (password: sheetdaily, disclosed on the Start Here tab so you can unlock if you ever need to). Sample plans are pre-filled so you can see exactly how it works; clear the yellow cells and type your own. Planning tool only — not financial, tax or retirement advice; a constant return is a simplification, taxes and other income are not modelled, and real markets arrive in a worse order than any spreadsheet’s.
Reviews
There are no reviews yet.